Nigeria’s Money Choices in 2026: Budgeting Through Higher Costs and Uncertainty
Households facing changing prices and borrowing costs can strengthen their finances by tracking cash flow, managing expensive debt and building realistic savings plans.


Nigeria’s Money Choices in 2026: Budgeting Through Higher Costs and Uncertainty
Personal finance decisions become harder when household expenses change faster than income. For Nigerians managing rent, transport, food, school fees and family commitments, a useful financial plan needs to be practical rather than perfect. The starting point is to understand where money goes, which obligations are most costly and how much flexibility remains after essential expenses.
Start With a Realistic Cash-Flow Picture
Record income and expenses over at least one full month, including irregular payments and small daily purchases. Separate essential commitments—such as housing, food, utilities and transport—from discretionary spending. The aim is not to eliminate every pleasure, but to make trade-offs visible before money is committed.
People with irregular earnings may find it useful to plan around a conservative estimate of monthly income and treat unusually strong months as an opportunity to rebuild reserves or pay down expensive debt.
Prioritise High-Cost Debt
Debt should be assessed by its effective cost, repayment schedule, penalties and consequences of missing a payment. Where several debts exist, paying extra toward the highest-cost balance can reduce total interest, provided minimum payments on other obligations remain current. Borrowers should contact lenders early if repayment is becoming difficult and should be cautious about taking a new loan merely to cover routine expenses.
Compare the full cost of credit, not only the advertised monthly payment. Fees, insurance, penalties and the length of the repayment period can make a seemingly manageable loan more expensive than expected.
Build an Emergency Reserve Gradually
An emergency fund helps households respond to medical bills, urgent repairs or a temporary loss of income without immediately borrowing. The appropriate target depends on job security, dependants and fixed costs. Starting with a modest, accessible amount is more realistic for many households than waiting until they can save several months of expenses at once.
Money needed soon should generally not be exposed to large market fluctuations. Before using a savings product, understand access restrictions, fees, institution protections and whether the promised return is guaranteed or variable.
Set Goals and Automate What You Can
Clear goals make saving easier to maintain. A household might set separate targets for school fees, rent, equipment for a small business or long-term retirement needs. Where income arrives regularly, an automatic transfer after payday can help; where income varies, a percentage-based approach may be more sustainable than a fixed amount.
Protect Against Scams and Unrealistic Returns
Promises of guaranteed high returns, pressure to recruit others or demands to transfer money quickly are warning signs. Verify financial institutions and investment products through relevant regulators, read the documentation and avoid committing money that is needed for essential expenses. A testimonial or social-media endorsement is not proof that an investment is legitimate.
A Practical Monthly Checklist
- Review income, fixed bills and variable spending.
- Check debt balances, interest rates and payment dates.
- Set aside a realistic amount for emergencies.
- Review savings goals and any upcoming large expenses.
- Verify any financial product before transferring money.
Conclusion
Good personal finance is less about predicting every economic change than building habits that withstand uncertainty. Tracking cash flow, reducing expensive debt, saving consistently and checking financial claims carefully can give households more control over their choices.
Sources and Further Reading
- Central Bank of Nigeria
- Securities and Exchange Commission Nigeria
- Nigeria Deposit Insurance Corporation
Editorial note: This article provides general financial education and is not individual financial advice. Verify current product terms and regulatory information before making decisions.
The Daily Brief
Get the daily FORBES.NG briefing.
Comments (0)
Sign in to join the conversation.
Related Stories
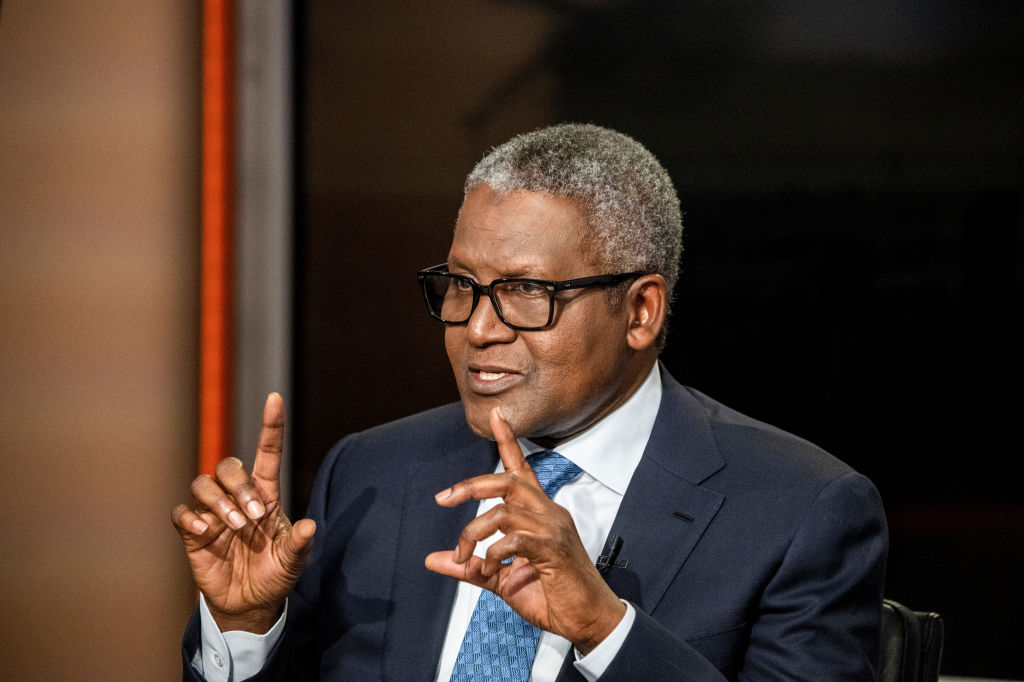
Africa’s Richest Man Confirms September London Secondary Listing Plans For Cement Behemoth
Dangote Cement, listed in Nigeria’s commercial capital Lagos, has a market capitalization of over $12 billion after its shares more than doubled over the past year. Africa’s richest man Aliko Dangote plans a secondary listing of his cement business in London in September, reviving long-standing plans to bring the continent’s largest cement producer to international …
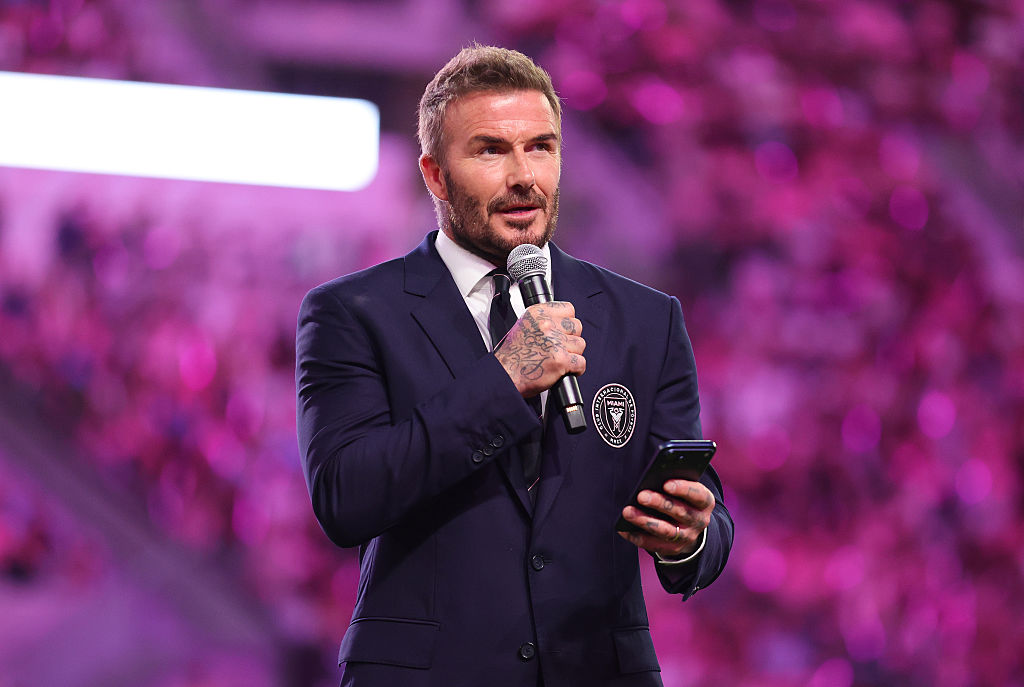
New Billionaire David Beckham On His Family, Team And Legacy
How the British super star built a $1 billion empire, mainly in the U.S., after retiring from soccer. This story was first published on Forbes.com It is 10 A.M. in Chiswick, a pleasant west London suburb, in late April, and Sir David Beckham has already been on set for two hours. This should have been expected: The …
Death And Taxes: Forbes’ Practical Guide For Families
Advice for survivors on everything from state inheritance and estate taxes to inherited IRAs to sorting through a lifetime of possessions and papers. Plus, sparing your own heirs. This article was first published on Forbes.com You expect the death of a spouse, parent or other close relative to be emotionally wrenching. What catches many survivors by …
More from Amara Nwosu

African Banks Face a New Test: Turning Digital Accounts Into Active Customers
Opening accounts digitally is only the first step. Banks must also make payments reliable, resolve customer problems quickly and build confidence in everyday digital financial services.

Africa’s Banking Sector: Digital Access Must Be Matched by Trust
Digital banking can widen access to financial services, but reliability, transparent fees, fraud prevention and effective complaint handling remain central to customer confidence.
Recommended



The Daily Brief